SystemFlow Financial Planning helps small business owners run the numbers that actually move a company forward.
Advisory consultations and planning engagements built around the cash, tax and forecasting questions that small Thai businesses face every month — not generic corporate templates.
Prefer to talk? Call +66-2-294-5817
Myth 01
“Financial planning is only worth it once the company is already large.”
This is the most common reason small owners postpone planning — and it is the most expensive one. A five-person trading firm on Rama III that cannot separate owner drawings from operating cash will burn through a quiet quarter far faster than a 200-staff manufacturer with the same blind spot, because the small firm has no buffer to absorb the mistake.
A planning engagement starts by mapping the cash that actually moves through your accounts each month: revenue lines, recurring costs, VAT payable, director remuneration and the personal funds you put back in. From there we can see which decisions are safe and which are quietly draining the business.
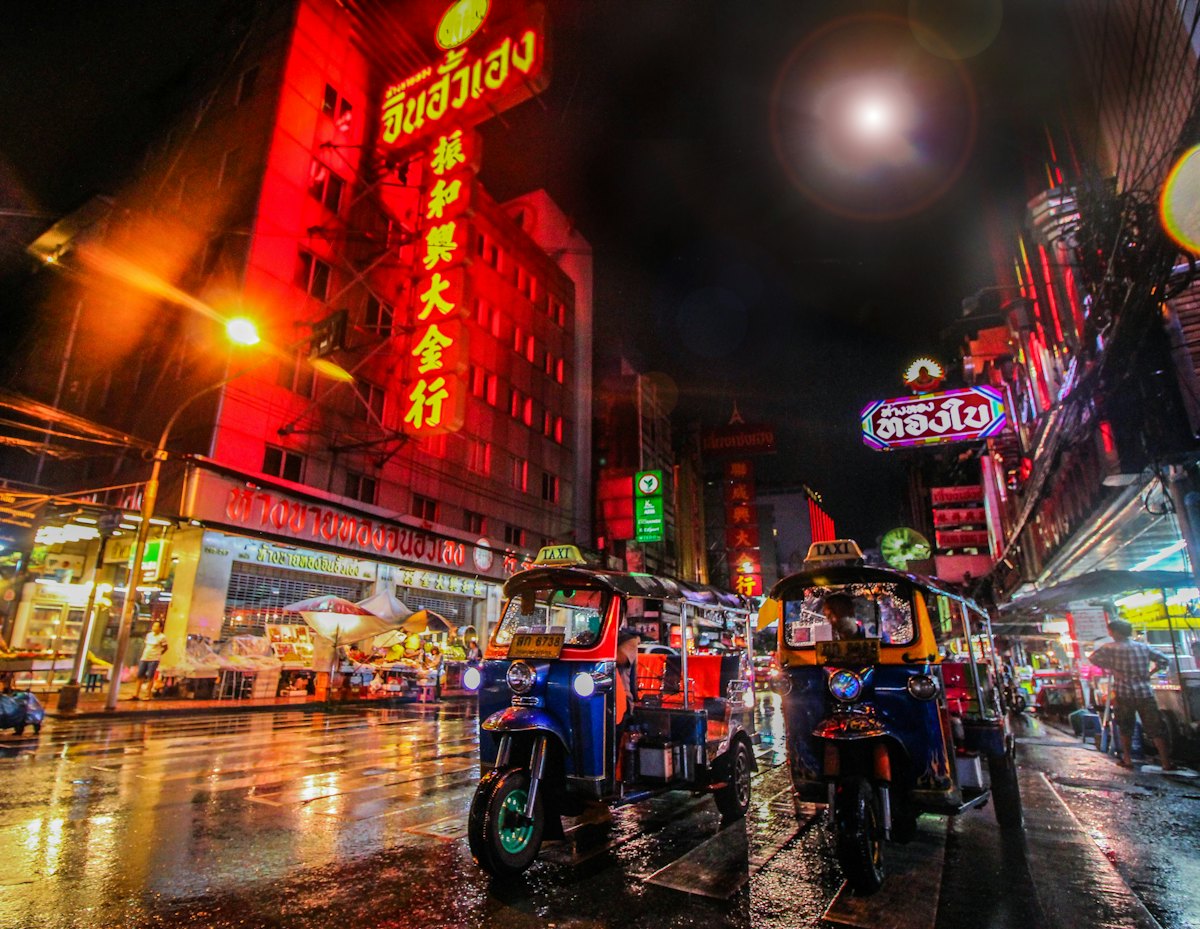
Built for Bangkok small businesses, not for a generic template.
Cash-flow rhythm, VAT cycles and personal-income-tax deadlines look different for a Yan Nawa trading firm than for a multinational. The plan should reflect that.
What a planning engagement looks like
Four working sessions, one plan you can actually run.
Discovery consultation
A 60-minute session to understand your business model, current cash position and the decisions you are putting off. No commitment to a full engagement yet.
Cash and tax mapping
We map monthly cash flow, VAT exposure and personal income tax obligations, then identify where owner drawings and operating costs are blurred together.
Planning engagement
A 12-month rolling plan covering cash reserves, tax timing, reinvestment and director remuneration — written so you can update it yourself between sessions.
Review and recalibration
A follow-up each quarter to compare plan against actuals, adjust for what changed, and re-time decisions around VAT and filing deadlines.
Myth 02
“My accountant already does this at year-end.”
Year-end accounting closes the books; it does not help you decide in November whether to take a director dividend or reinvest the cash before the VAT cycle turns. Many small owners discover, too late, that the profit shown on their filed accounts is not the cash they can actually spend.
A planning engagement sits between your daily operations and your year-end accountant. It gives you a forward view — what the next quarter looks like under two or three realistic scenarios — so the year-end filing holds fewer surprises and the tax you owe matches the cash you kept.
Good financial planning for a small business is not a forecast that turns out to be right. It is a plan clear enough that you can change it on a Tuesday when a customer pays late.— the principle behind every SystemFlow engagement